Car loan early settlement UAE rules are more favourable to borrowers than most people realise, and more favourable than a lot of published advice suggests. The UAE Central Bank caps the early settlement fee on a car loan at 1% of the outstanding balance, and a surprising number of borrowers never settle early because they have been told a much higher figure that applies to a different product entirely.
If you have a car loan and spare capital, the arithmetic is usually straightforward and usually in your favour. Here is how to work it out properly.
The 1% cap, and where the confusion comes from
Under the UAE Central Bank's Regulations Regarding Bank Loans and Other Services Offered to Individual Customers, the early settlement charge on a car loan is capped at 1% of the outstanding balance. Advance payment of instalments is similarly capped at 1% of the instalment.
The regulation is published in the UAE Central Bank's own rulebook, under its Regulations Regarding Bank Loans and Other Services Offered to Individual Customers.
Two sources of confusion regularly cost borrowers money. Mortgages have historically carried a different and higher charge structure, and mortgage-focused advice circulates widely, but it does not apply to car loans. Personal loans carry a cap of 1% subject to a maximum of AED 10,000, which is a separate rule again.
| Product | Early settlement cap |
|---|---|
| Car loan | 1% of outstanding balance |
| Personal loan | 1%, maximum AED 10,000 |
| Advance instalment payment | 1% of the instalment |
Source: UAE Central Bank, Regulations Regarding Bank Loans & Other Services Offered to Individual Customers.
Always confirm the figure in your own loan agreement and the current regulation before acting. Your bank's Key Facts Statement sets out the charge that applies to your specific facility, and regulations are periodically amended.
Working out whether it is worth it
The calculation has three inputs: your outstanding balance, the remaining profit or interest you would otherwise pay, and the settlement fee.
The basic test:
Remaining interest/profit you would pay − settlement fee = your saving
Worked through with round numbers for illustration:
| Item | Example figure |
|---|---|
| Outstanding balance | AED 60,000 |
| Remaining interest/profit over the rest of the term | AED 6,500 |
| Settlement fee at 1% of outstanding | AED 600 |
| Net saving | AED 5,900 |
Illustrative example only, your figures will differ. Ask your bank for a formal settlement quotation.
The critical point: on most car loans the fee is small relative to the interest saved, so early settlement is usually worthwhile provided you genuinely have the capital spare.
Get two things from your bank in writing first: a formal settlement quotation valid to a stated date showing principal, fee and total payable; and confirmation of how remaining profit is treated, since Islamic and conventional structures calculate the outstanding amount differently and that affects the saving.
Model scenarios with the car loan calculator; our UAE car loan and finance guide covers loan structures in more depth.
The settlement process step by step
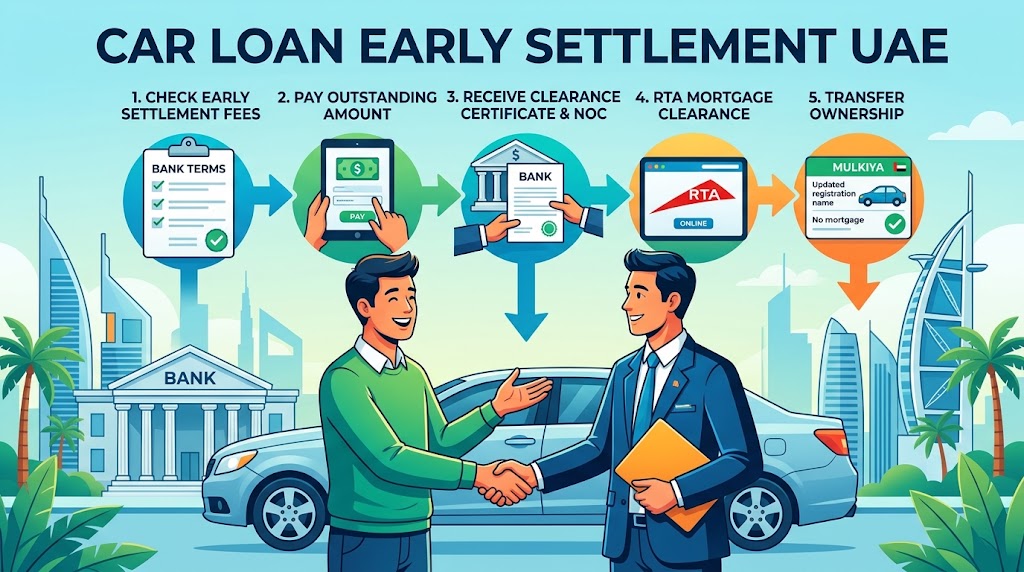
1. Request a settlement quotation for your auto finance facility. It will state a figure valid until a specific date.
2. Check the fee against the cap. Confirm the charge does not exceed 1% of outstanding balance; if it appears to, ask the bank to explain the calculation in writing.
3. Pay before the quotation expires. Settlement figures are date-sensitive because profit accrues daily.
4. Obtain written confirmation of closure, a formal letter confirming zero balance, not just a payment receipt.
5. Request the No Objection Certificate (NOC). This is the document that matters most.
6. Complete the vehicle release with the traffic authority, removing the bank's interest from the registration.
7. Verify the Mulkiya no longer shows a mortgage or lien.
Releasing the vehicle: NOC and Mulkiya
Settling the loan and releasing the car are two separate things, and this is where people get caught. While a loan is outstanding the bank's interest is recorded against the vehicle, and until that is formally removed you cannot freely sell or transfer the car, even if the loan is fully paid.
What you need:
- A No Objection Certificate from the bank, confirming it has no further claim on the vehicle.
- Formal removal of the bank's interest from the registration record at the relevant traffic authority. For Dubai this is handled through the RTA, and rta.ae publishes the current requirements.
- An updated Mulkiya showing no mortgage or lien.
Allow time for this. Banks typically take some days to issue an NOC after settlement, and the registration update is a separate appointment. If you are settling in order to sell the car, start the process well before you list it. Our guide on selling a financed car in the UAE covers the alternative route where the buyer's payment clears the loan directly.
If you plan to sell afterwards, the free car valuation tool gives you a market-based figure, and sell my car is the fastest route to listing.
Partial settlement as an alternative
You do not have to settle the whole loan. Most UAE banks allow partial early payments, which reduce the principal and therefore the interest accruing on it.
Partial settlement is worth considering when:
- You have surplus capital but want to retain a reserve
- You want to reduce the monthly instalment rather than clear the debt
- You want to shorten the term while keeping the instalment the same
Ask your bank explicitly which of those two outcomes a partial payment produces: reduced instalment or reduced term. They are not the same, the saving differs substantially between them, and banks do not always apply the option you assumed.
When early settlement is a bad idea
Early settlement is not automatically correct. Think twice when:
It exhausts your emergency reserve. Clearing a loan at 1% fee is a poor trade if it leaves you borrowing at credit-card rates three months later.
The capital has a better use. If the money is earning or saving you more elsewhere than the loan's rate costs you, keep the loan.
You are close to the end of the term. On a loan with a few months left, most interest has already been paid. The saving may not justify the fee and the administrative effort.
Your loan carries an unusually low promotional rate. Some manufacturer-subsidised finance runs at rates low enough that settling early makes little sense.
Frequently asked questions
How much is the early settlement fee on a car loan in the UAE?
The UAE Central Bank caps the early settlement charge on a car loan at 1% of the outstanding balance. Personal loans are capped at 1% up to a maximum of AED 10,000, which is a different rule. Always confirm the figure in your own loan agreement and Key Facts Statement, as these are the terms that apply to you.
Is it worth paying off a car loan early in the UAE?
Usually, if you genuinely have the capital spare. With the settlement fee capped at 1% of outstanding balance, the interest saved over a remaining term typically exceeds the fee comfortably. It is less attractive if it exhausts your emergency savings, if the loan is nearly finished, or if the rate is unusually low.
What is an NOC for a car loan?
A No Objection Certificate is a letter from your financing bank confirming it has no further claim on the vehicle. You need it to have the bank's interest removed from the vehicle registration, which must happen before you can freely sell or transfer the car. Settling the loan alone is not sufficient.
Can I make a partial early payment on a UAE car loan?
Most UAE banks permit partial early settlement, which reduces the outstanding principal. Ask your bank explicitly whether the payment reduces your monthly instalment or shortens the term, as the saving differs significantly between the two outcomes and the default applied is not always the one you expected.
How long does it take to release a car after settling the loan?
Banks typically take several days to issue the No Objection Certificate after settlement, and removing the bank's interest from the registration record with the traffic authority is a separate step requiring its own appointment. If you are settling in order to sell, begin the process well before listing the vehicle.
Take control of your car finance
The 1% cap makes early settlement a genuinely good deal for most UAE car-loan borrowers, far better than the mortgage-focused figures that circulate widely would suggest. Get a formal settlement quotation, check it against the cap, and do not forget that clearing the loan and releasing the car are two separate steps.
Model your options with the car loan calculator, and if settling means you are ready to change cars, check what yours is worth with the free car valuation tool, read our guide to selling a car in Dubai, then browse used cars across the UAE or the latest new car listings.